
Property foreclosures in Florida are a complex and sometimes overwhelming process, but understanding how it works across all counties in 2026 can help homeowners, investors, and real estate professionals make informed decisions. Florida is a judicial foreclosure state, meaning that foreclosures must go through the courts, and the process may vary slightly depending on the county. This article explains the Florida property foreclosure process, county-specific differences, homeowner rights, and tips for investors.
Understanding Property Foreclosure in Florida
What is Foreclosure?
Foreclosure is the legal process by which a lender or government authority takes ownership of a property after the homeowner fails to meet financial obligations, such as mortgage payments or property taxes. In Florida, most foreclosures are judicial, meaning a lawsuit is filed, and the process takes place under court supervision. Some foreclosures can also occur due to tax liens or HOA dues.
Why Foreclosures Happen
Homeowners may face foreclosure for several reasons, including missed mortgage payments, unpaid property taxes, or outstanding Homeowners Association fees. Economic factors, job loss, or unexpected financial hardships can also trigger a foreclosure. Understanding these triggers is essential for both homeowners seeking solutions and investors tracking potential properties.
Legal Framework in Florida
Florida foreclosures are governed under Chapter 45 of the Florida Statutes, which outlines the procedures for mortgage foreclosures. The law ensures due process for homeowners, requires proper notice, and mandates judicial review before a property can be sold at a public auction. Every county follows this framework but may have slight variations in timelines or auction procedures.
Overview of Florida’s Counties and Foreclosure Variations
Florida is made up of 67 counties, each with unique rules and timelines for foreclosure. Some counties have faster judicial processing, while others may experience delays due to higher caseloads.
- Miami-Dade County – Fast-growing real estate market, online auction portals.
- Broward County – Slightly slower judicial processing, mediation programs.
- Palm Beach County – High foreclosure activity, public notice requirements.
- Hillsborough County – Courts process foreclosures efficiently, short notice period.
- Orange County – Specialized programs for distressed homeowners.
- Pinellas County – Detailed auction listing rules, online access.
- Duval County – Judicial timelines vary; mediation programs available.
- Lee County – Auction procedures are well-documented; property title research needed.
- Polk County – Tax lien foreclosures are common, redemption periods apply.
- Brevard County – Fast-track auctions for delinquent properties.
Understanding county-specific rules ensures homeowners are aware of deadlines and investors can make informed decisions.
Florida Foreclosure Statistics by County
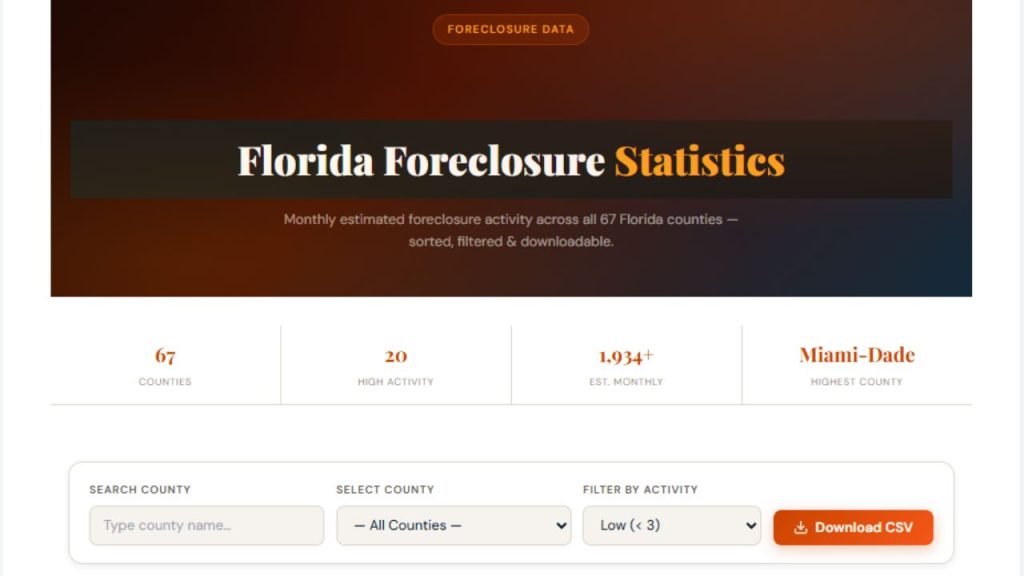
Florida’s foreclosure activity varies widely across its 67 counties, with some areas experiencing high monthly averages while others see minimal activity. Understanding these county-level trends is essential for homeowners, investors, and real estate professionals to anticipate foreclosure risks, track opportunities, and make informed decisions about property management or investment strategies.
Florida Foreclosure Statistics
Monthly estimated foreclosure activity across all 67 Florida counties — sorted, filtered & downloadable.
| County | Est. Monthly Foreclosures | Activity Level | Volume Bar |
|---|
No counties match your filter.
Step-by-Step Florida Foreclosure Process
Step 1 – Notice of Default
The foreclosure process begins when the lender sends a Notice of Default to the homeowner after missed payments, typically 90 days of delinquency. This notice informs the homeowner of the overdue amount and provides an opportunity to cure the default before legal action begins.
Step 2 – Filing a Lis Pendens
Once a foreclosure lawsuit is filed, the lender records a Lis Pendens with the county clerk. This notice informs the public that the property is subject to legal action and prevents the homeowner from selling or refinancing without resolving the foreclosure.
Step 3 – Foreclosure Complaint and Summons
The lender files a formal foreclosure complaint in the county court. The homeowner receives a summons and has 20 days to respond. Failure to respond may result in a default judgment, giving the lender the right to proceed to auction.
Step 4 – Homeowner Response & Mediation Options
Florida law encourages homeowners to explore alternatives. Many counties provide mediation programs or settlement options to prevent foreclosure. Homeowners can challenge errors, negotiate repayment plans, or request loan modifications to stay in their home.
Step 5 – Court Judgment & Final Foreclosure Order
If no settlement is reached, the court issues a final judgment of foreclosure. This judgment sets the stage for the property to be sold at a public auction. The court ensures all notices and legal requirements have been met before approving the sale.
Step 6 – Public Auction
Foreclosed properties are sold at a public auction to the highest bidder. Each county has its own auction process, often online or at the courthouse. Bidders must register in advance, and sales are typically cash or certified funds only.
Step 7 – Post-Auction Procedures
After the auction, the winning bidder receives a Certificate of Sale. Florida allows a redemption period for certain tax-related foreclosures, but mortgage foreclosures usually transfer ownership immediately. The new owner must handle title transfers and property management.
County-Specific Variations in Foreclosure
Miami-Dade County
Foreclosures in Miami-Dade are managed efficiently with online auction portals. Average timelines range from 9 to 12 months, depending on court schedules.
Broward County
Broward emphasizes mediation and loss mitigation. Judicial timelines are slightly slower, and homeowners may have additional opportunities to negotiate repayment.
Palm Beach County
High foreclosure activity makes timely notice critical. Homeowners are strongly advised to monitor local court records for upcoming sales.
Hillsborough County
Hillsborough offers a relatively fast foreclosure process, typically under 10 months. Public auctions are well-advertised, allowing investors to participate confidently.
Orange County
Orange County provides alternative programs for homeowners, including loan modification support and short-term repayment plans to prevent foreclosure.
(Other counties follow similar steps but may differ slightly in auction processes, online availability, and notice requirements.)
Foreclosure Alternatives for Florida Homeowners
Short Sale
A short sale allows homeowners to sell their property for less than the mortgage balance with lender approval. This can prevent foreclosure from appearing on credit reports and may be faster than the judicial process.
Deed in Lieu of Foreclosure
Homeowners can voluntarily transfer ownership to the lender through a deed in lieu of foreclosure. This approach avoids lengthy court proceedings but may impact future credit.
Loan Modification & Repayment Plans
Florida homeowners may qualify for loan modifications, adjusting interest rates or repayment schedules. Many counties have programs to help struggling homeowners stay in their homes legally and financially.
Role of Tax Liens and Delinquent Taxes
Unpaid property taxes in Florida can lead to tax lien foreclosures, separate from mortgage foreclosures. Counties sell tax liens at public auctions, allowing investors to purchase the lien and collect interest or eventually acquire the property if unpaid. Tax lien rules and redemption periods vary by county, making it essential to research local procedures.
Protecting Homeowner Rights During Foreclosure
Homeowners have several legal protections, including:
- Right to notice – must be informed at every stage.
- Right to mediation – many counties require lenders to offer alternatives.
- Right to contest errors – property value miscalculations or procedural errors can be challenged.
Avoiding scams is also crucial. Many fraudulent investors target distressed homeowners, so always verify the legitimacy of any offer.
Tips for Investors Interested in Florida Foreclosures
- Research County Records – Understand auction procedures and timelines for each county.
- Check Online Portals – Many counties provide online listings of foreclosure properties.
- Understand Redemption Periods – Tax lien foreclosures may have redemption rights, delaying ownership transfer.
- Conduct Due Diligence – Inspect properties, check liens, and evaluate repair costs before bidding.
- Stay Updated – Florida foreclosure laws can change; staying informed ensures compliance and investment security.
Conclusion
The Florida property foreclosure process in 2026 requires careful navigation by homeowners and investors alike. While the state follows a judicial foreclosure framework, county-specific rules, timelines, and auctions make understanding local procedures essential. Homeowners have multiple alternatives to avoid foreclosure, including short sales, loan modifications, and mediation programs, while investors must conduct thorough research before participating in auctions. Staying informed about Florida’s laws and county-specific differences is the key to protecting property rights and making smart real estate decisions.
Frequently Asked Questions (FAQs)
1. How long does foreclosure take in Florida?
Typically 9–12 months for mortgage foreclosures, but timelines may vary by county and case complexity.
2. Can I stop foreclosure after a notice of default?
Yes, homeowners can negotiate repayment, request mediation, or pursue loan modifications before the court judgment.
3. What is the redemption period in Florida foreclosures?
Mortgage foreclosures generally have no redemption period, but tax lien foreclosures may allow 30–60 days for repayment.
4. Are foreclosure auctions public?
Yes, all Florida foreclosure auctions are public, with many counties offering online participation for investors.
5. How do county laws differ across Florida?
Timelines, auction methods, and mediation programs vary by county, making local research essential for both homeowners and investors.

